Crypto vs. Credit Cards: Which Payment Method Is Better for Small Businesses?
For small businesses, payments are more than a checkout detail. The method you accept affects costs, settlement speed, customer convenience, fraud exposure, reporting, cross-border growth and overall cash flow. As more businesses explore digital commerce and international selling, the question is no longer whether credit cards matter. They clearly do. The bigger question is whether crypto payments should also be par…

About This Article
For small businesses, payments are more than a checkout detail. The method you accept affects costs, settlement speed, customer convenience, fraud exposure, reporting, cross-border growth and overall cash flow. As more businesses explore digital commerce and international selling, the question is no longer whether credit cards matter. They clearly do. The bigger question is whether crypto payments should also be part of the mix.
This guide compares crypto payments and credit card payments across the factors that matter most to small businesses: payment processing costs, settlement, chargebacks, fraud exposure, transaction finality, cross-border payments, customer reach and volatility. The goal is not to crown a universal winner. It is to help business owners understand where each option performs best, and why many businesses may eventually benefit from offering both.
The Short Answer
Credit cards remain the most familiar and widely accepted payment method for everyday commerce, especially for local retail, mainstream consumer checkout and buyers who expect traditional payment protections. Crypto, however, can be especially attractive for international and digital commerce because it can support borderless transfers, alternative settlement models, 24/7 networks and stablecoin-based payments. For many small businesses, the strongest strategy is not crypto instead of cards. It is crypto alongside cards.
If you want to learn more about the Miracle Pay crypto-payment ecosystem and request a demo, Click here to request a demo.
Why This Comparison Matters
Small businesses are operating in a market where customers expect fast checkout, flexible payment choices and digital convenience. They may also want to reach customers outside their home country, reduce friction in digital transactions, or experiment with newer payment rails. A thoughtful payment strategy can help a business:
- serve more customer preferences;
- expand into online and international markets;
- manage transaction costs and settlement expectations;
- reduce overreliance on any single payment channel; and
- position the business for future digital commerce opportunities.
At-a-Glance Comparison
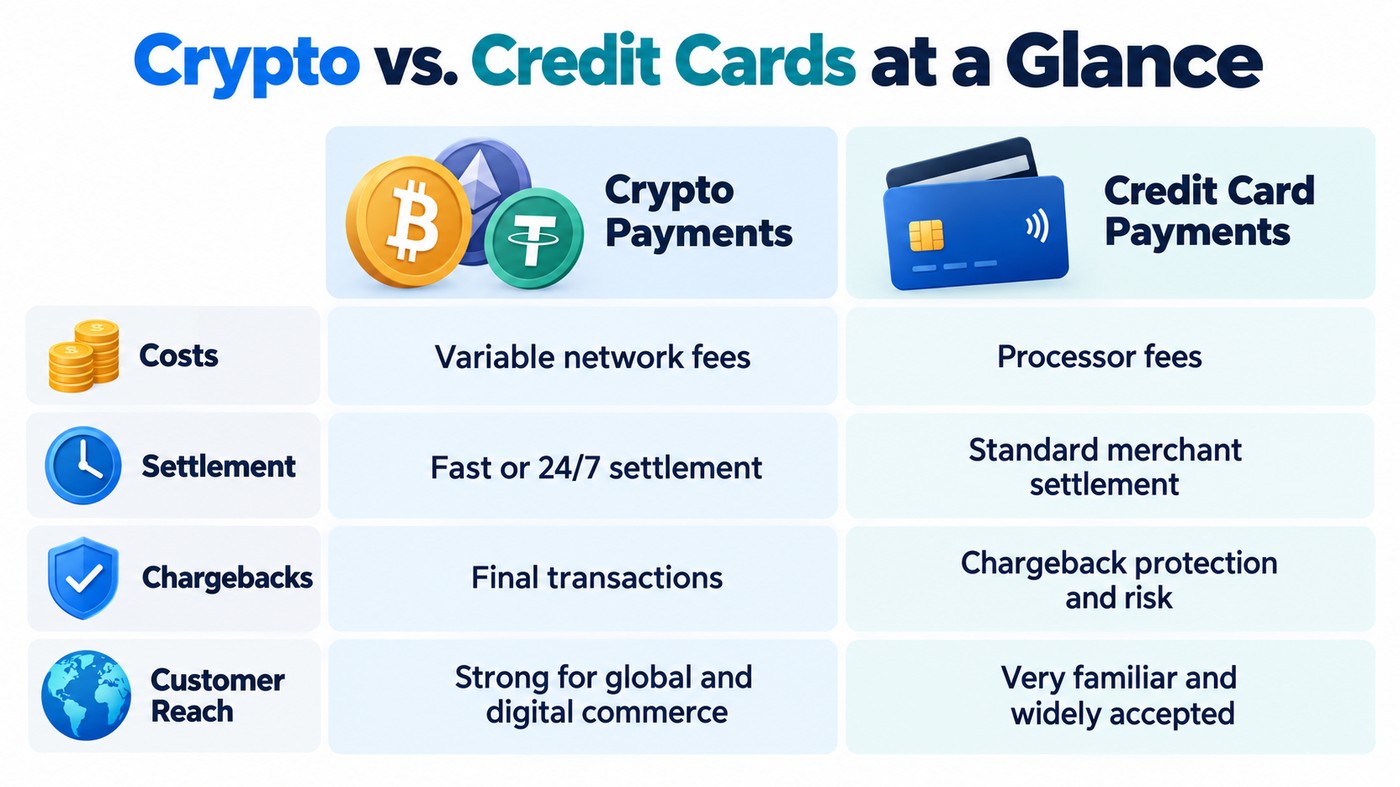
| Category | Crypto Payments | Credit Cards |
|---|---|---|
| Processing Costs | Can involve network fees, wallet or gateway costs, and possible conversion fees. | Typically include processor fees, interchange and related merchant costs. |
| Settlement | May settle quickly or on a 24/7 basis, depending on the network and provider. | Familiar merchant settlement workflows, but usually dependent on banking and processor timelines. |
| Chargebacks | Transactions are often final, which can reduce chargeback exposure but also reduces reversal flexibility. | Chargebacks and dispute systems are well established, which can help customers but may increase merchant risk and administrative burden. |
| Cross-Border Payments | Often attractive for international and digital commerce because blockchain-based transfers can be borderless. | Widely used, but international acceptance, currency conversion and additional friction may apply depending on market and processor setup. |
| Customer Reach | Can appeal to crypto users, digital-first buyers and global customers. | Broadly familiar to mainstream consumers and often expected at checkout. |
| Volatility | Can be managed with stablecoins or instant conversion, but volatility must be considered when accepting non-stable assets. | Generally denominated in fiat currency, creating more pricing certainty for merchants and buyers. |
Processing Costs: Which Option Is More Cost Effective?
Credit card processing costs are familiar to most small businesses. Merchants often pay a combination of processing charges, interchange fees and related service costs. The advantage is predictability. The disadvantage is that these costs can feel embedded into nearly every transaction.
Crypto payments may involve blockchain network fees, payment gateway charges and, in some cases, conversion fees when crypto is automatically converted into fiat. Depending on the asset and network used, crypto costs may be low, moderate or occasionally unpredictable. This means cost comparison is not always simple. A business accepting low-cost stablecoin payments may see one outcome, while a business relying on another network may see something different.
Bottom line: neither method is automatically cheaper in every situation. Business owners need to compare the actual cost structure of the specific processor, network and settlement model they plan to use.
Settlement Speed and Cash-Flow Impact
Settlement speed matters because it affects how quickly a business can access funds. Crypto is often attractive here because blockchain networks can run 24/7 and do not depend on traditional banking hours. That can be useful for online sellers, digital service businesses and merchants serving international customers.
Credit card settlement is familiar and well integrated into accounting workflows, but it usually follows more traditional processor and banking timelines. For many businesses, that is perfectly acceptable. For others, especially digital-first companies, the appeal of always-on payment networks can be significant.
Chargebacks, Disputes and Transaction Finality
One of the most important differences between crypto and credit cards is transaction finality. Crypto transactions are often final once confirmed. That can reduce chargeback risk for merchants, but it also means there is less flexibility if a mistake, refund issue or customer-service problem arises.
Credit cards offer mature dispute and chargeback systems. From the customer perspective, that can feel safer and more familiar. From the merchant perspective, it can create added risk, fraud exposure and administrative work. Small businesses dealing with high dispute rates may find this issue especially important.
Bottom line: crypto can help reduce chargeback exposure, while cards can offer dispute structures customers already know and trust.
Why Crypto Can Shine in International and Digital Commerce
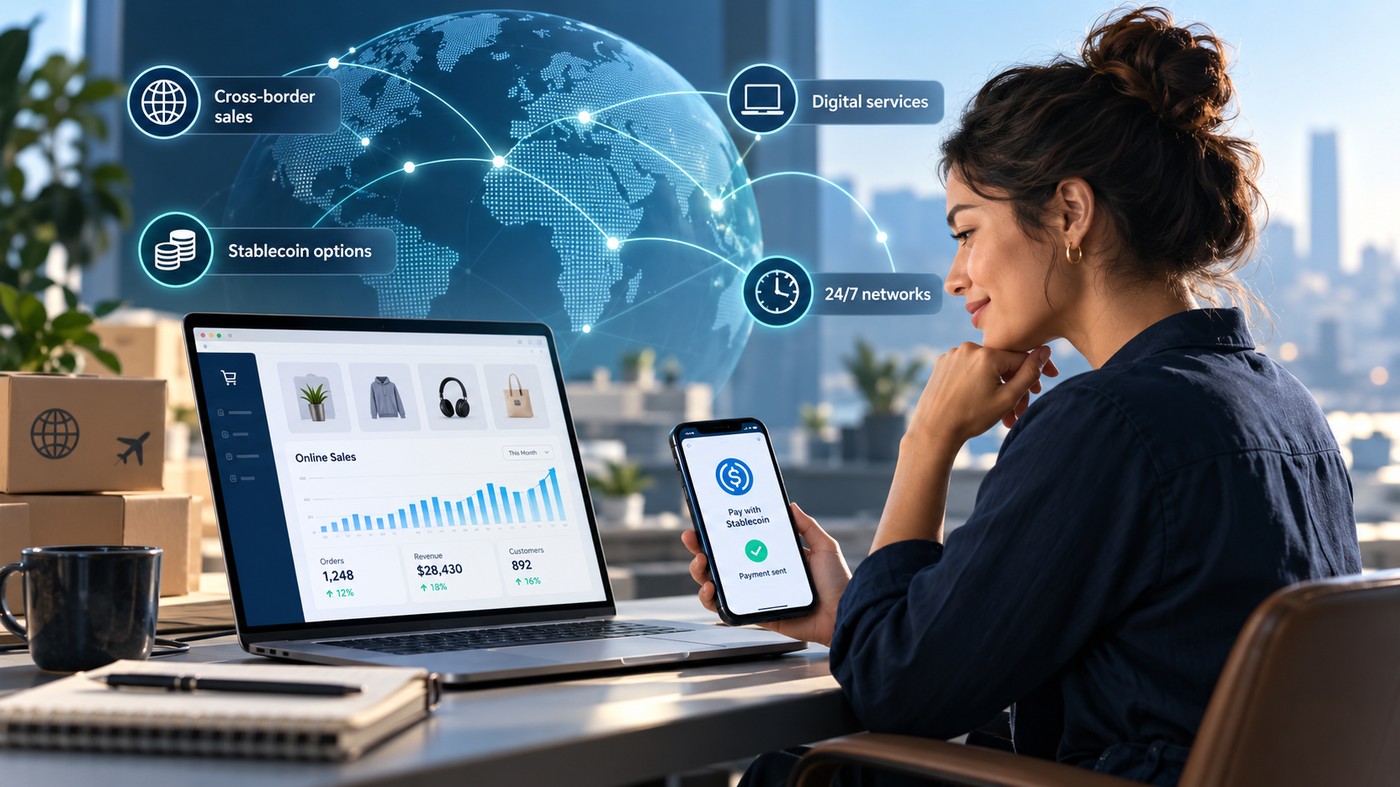
Crypto tends to be most compelling when a business operates online, serves digital customers, or wants to reach people across borders. In those scenarios, traditional payments may involve more layers of friction, including currency conversion, banking schedules or international card-processing complexity.
Crypto can be especially useful when:
- the business sells digital products or services;
- customers are international or crypto-native;
- the merchant wants access to 24/7 payment networks;
- stablecoin payments offer a practical middle ground between innovation and stability; or
- the business wants to experiment with alternative payment rails without replacing its existing setup.
Stablecoins deserve special attention because they can reduce the volatility problem while preserving many of the benefits of blockchain-based transfer systems. For small businesses, stablecoins may be one of the most practical entry points into crypto payments.
Where Credit Cards Still Have a Strong Advantage
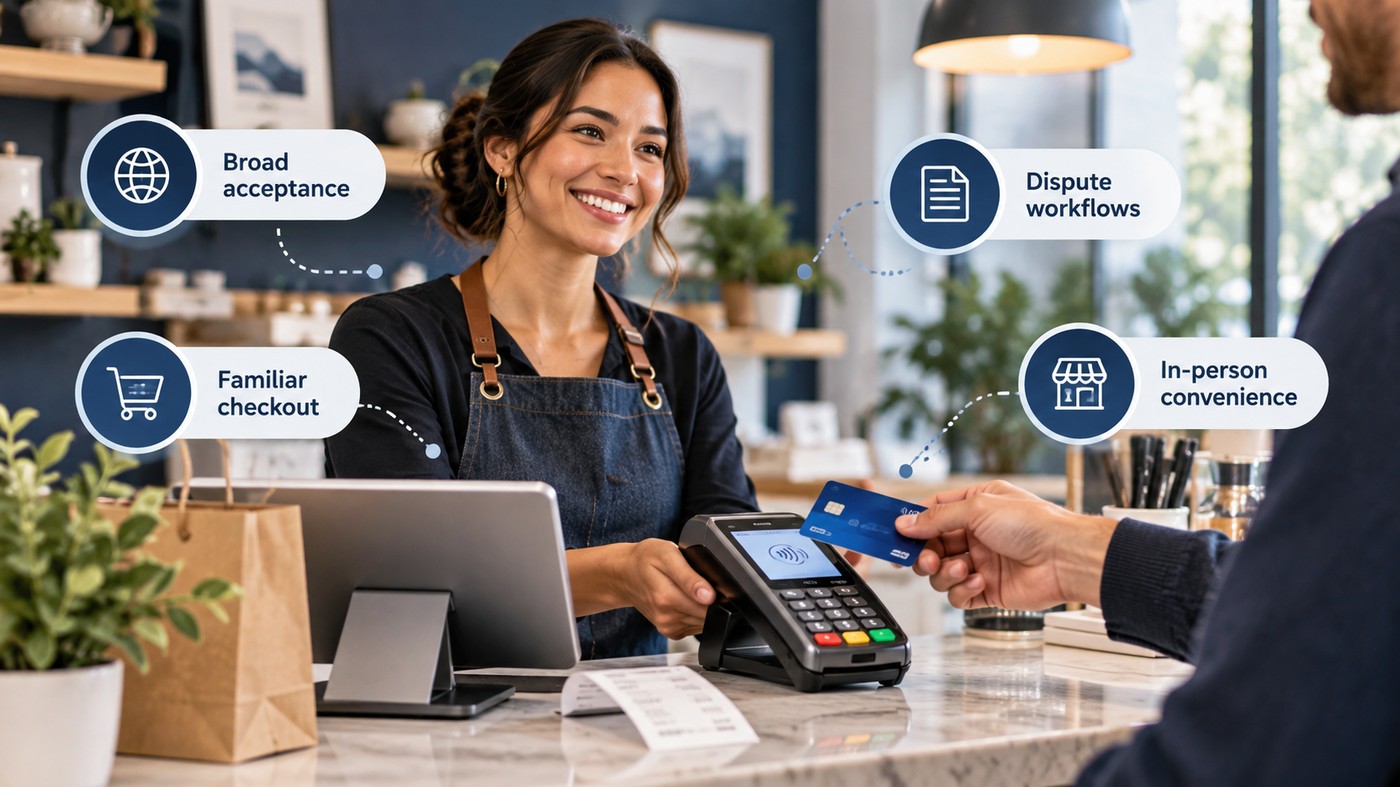
Credit cards remain highly effective for local and mainstream commerce. They are familiar, trusted and widely expected. They also fit naturally into in-person retail, everyday consumer checkout and industries where conventional dispute workflows matter.
Credit cards may still be preferable when:
- your customers are primarily local or non-technical;
- your business depends on familiar in-person checkout behavior;
- you want conventional refund and dispute pathways;
- your accounting and operations are built around standard merchant-processing systems; or
- you need the broadest immediate consumer recognition possible.
Fraud Exposure and Risk Management
No payment system eliminates risk. Credit cards can expose merchants to certain types of fraud and chargeback abuse, but they also come with well-developed controls and established monitoring ecosystems. Crypto reduces some categories of merchant chargeback risk because of transaction finality, but it introduces other operational concerns such as wallet security, private-key safety, onboarding complexity and the possibility of sending or receiving funds incorrectly.
Risk management therefore depends less on ideology and more on implementation. The better question is not “Which payment system is risk-free?†The better question is “Which risks can my business manage most effectively?
Volatility: The Issue That Changes the Conversation
Volatility is one of the biggest reasons businesses hesitate to accept crypto. If a company receives a volatile digital asset and holds it, the value may rise or fall quickly. That uncertainty can complicate pricing and cash-flow planning. This is why many businesses considering crypto start with one of two approaches:
- accepting stablecoins instead of more volatile assets; or
- using a provider that supports automatic crypto-to-fiat conversion.
With the right setup, volatility does not have to be a deal-breaker. But it should never be ignored.
So Which Payment Method Is Better?
The honest answer is: it depends on the business model.
- Credit cards are often better for mainstream local commerce, broad consumer familiarity and conventional checkout behavior.
- Crypto can be better for international and digital commerce, stablecoin-driven experimentation, alternative settlement models and reaching crypto-friendly audiences.
- Both together may be the strongest option for many modern small businesses.
If your business wants flexibility, the goal should not be to force one payment model into every situation. It should be to understand what each method does well, then build a payment stack that supports your customers and your growth strategy.
Exploring Crypto Payment Infrastructure
Businesses that want to explore crypto payment solutions, stablecoin workflows or digital-commerce infrastructure should evaluate features such as supported networks, settlement choices, reporting, security controls, conversion options and customer experience. If you want to learn more about the Miracle Pay crypto-payment ecosystem and request a demo, Click here to request a demo.
Final Thoughts
Crypto is not universally superior, and credit cards are not outdated. Each plays a meaningful role in small-business commerce. Cards continue to dominate everyday consumer expectations. Crypto offers strategic advantages in digital and international settings, especially when stablecoins and conversion tools are part of the setup.
The best decision is the one aligned with your customers, your business model and your risk tolerance. If you want to explore how crypto payments could fit into your business strategy, Click here to request a demo.